Midland residents face challenges repaying loans, especially Midland title loans due to high interest rates (up to 400%) and short terms (30 days). Volatile local market and rising property values exacerbate risks. To mitigate these issues, residents should explore alternative financing, understand loan terms, maintain vehicle resale value, create budgets, seek financial advice, negotiate rates, consolidate debt, and utilize community resources for tailored repayment plans to avoid repossession and financial strain.
Midland residents, like many across the country, face mounting financial challenges, with loan repayment often topping their concerns. In this authoritative piece, we delve into the reasons why certain Midland dwellers struggle to repay loans, specifically focusing on the prevalence of Midland title loans and their unique implications. These short-term, high-interest credit options, while attractive in urgency, can trap borrowers in a cycle of debt. We explore practical solutions and strategies to alleviate this burden, offering valuable insights for both current and prospective loan borrowers.
- Understanding Midland's Economic Landscape: Factors Affecting Loan Repayments
- Midland Title Loans: How These Short-Term Solutions Can Escalate Financial Strain
- Strategies for Midland Residents: Overcoming Loan Repayment Challenges and Building Stability
Understanding Midland's Economic Landscape: Factors Affecting Loan Repayments
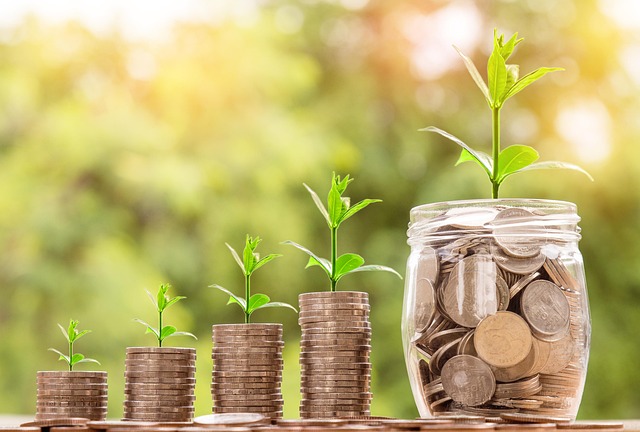
Midland’s economic landscape plays a significant role in understanding why some residents face challenges when repaying loans, particularly Midland title loans. The city’s unique financial environment is characterized by a mix of industries, including energy, healthcare, and education, which can both support and complicate residents’ financial health. According to recent data, the unemployment rate in Midland has been relatively stable but remains higher than some neighboring cities like Fort Worth, where job opportunities are more abundant. This disparity can create economic pressures for Midland residents seeking short-term financial solutions.
One key factor affecting loan repayments is the local market’s volatility. Midland’s economy heavily relies on sectors that experience fluctuations, such as energy. When commodity prices waver, it directly impacts local businesses and households, potentially leading to reduced incomes and increased stress on existing loans. For instance, a sudden drop in oil prices can cause energy-related industries to downsize, affecting employment rates and the overall financial stability of Midland residents who rely on these sectors for their livelihoods. This volatility makes it challenging for borrowers to maintain consistent repayment plans, especially when facing unexpected financial setbacks.
Additionally, Midland’s property values and housing market dynamics influence loan requirements. The city has experienced steady growth in home values over the past decade, but this can create a challenge for homeowners seeking Title Transfer loans. As property values rise, so do the expectations for collateral and loan amounts, potentially burdening borrowers with larger debts. In contrast, Fort Worth Loans offer more flexible terms and lower interest rates, making them an attractive alternative for Midland residents looking to avoid stringent repayment conditions associated with some local title loan providers.
To navigate these financial challenges, Midland residents should consider the following: (1) explore alternatives to title loans, such as traditional bank loans or credit unions, which often have more favorable terms; (2) understand the full scope of loan requirements and potential fees before signing any agreement; and (3) seek expert advice from financial counselors to create personalized repayment plans that align with their economic reality. By adopting these strategies, Midland residents can better manage their loan repayments and maintain long-term financial stability despite the unique economic factors shaping their city’s landscape.
Midland Title Loans: How These Short-Term Solutions Can Escalate Financial Strain
Midland residents, like many others across the country, face a range of financial challenges that can make loan repayment a daunting task. One particular type of loan that has gained attention for its potential to exacerbate financial strain is the Midland title loan. These short-term lending solutions, which often require individuals to use their vehicle or boat titles as collateral, present a complex web of risks and consequences for borrowers.
The appeal of Midland title loans lies in their perceived accessibility; these loans are typically easier to obtain than traditional bank loans, with fewer stringent credit requirements. However, this ease of access comes at a high cost. Interest rates on such loans are notoriously high, often exceeding 300% annually. What’s more, borrowers are at risk of losing their collateral if they fail to repay the loan within the specified timeframe. This creates a vicious cycle where individuals, already facing financial strain, find themselves in an even more precarious position, struggling to make ends meet and repay the mounting debt.
Consider the example of Boat Title Loans, a specific type of Midland title loan popular among those who own recreational vehicles. According to recent data, average interest rates on these loans can reach up to 400%, with repayment terms as short as 30 days. This means borrowers must find substantial funds in an extremely limited time frame. When individuals are unable to repay, lenders have the right to repossess the vehicle, leaving the borrower with not only lost collateral but also a damaged credit score and potential legal repercussions. To mitigate these risks, Midland residents should explore alternative loan options and carefully consider the implications of using their assets as collateral.
Strategies for Midland Residents: Overcoming Loan Repayment Challenges and Building Stability
Many Midland residents face challenges when it comes to loan repayment due to economic factors and personal circumstances. This is particularly true for those relying on Midland title loans, which, while offering quick approval, can lead to a cycle of debt if not managed properly. The Title Loan Process, with its concise requirements and relatively fast turnaround, might seem appealing in the moment, but it’s essential to understand that these short-term solutions often require meticulous planning for successful repayment.
Overcoming these challenges necessitates a multi-faceted approach. For starters, Midland residents should consider the frequency of vehicle inspections – a crucial aspect of many title loans – as an opportunity to maintain their vehicle’s condition, which can lead to better resale value and reduced loan amounts. By keeping their vehicles in top shape, they may negotiate lower interest rates and extend their loan terms, easing repayment strain. Additionally, creating a detailed budget is paramount. Tracking income, fixed expenses, and variable costs allows individuals to identify areas for adjustment, freeing up funds for loan repayments without sacrificing essential living costs.
Seeking expert advice from financial counselors or community resources can also be invaluable. These professionals offer strategies tailored to individual circumstances, whether it’s negotiating with lenders, exploring debt consolidation options, or learning about government assistance programs. For instance, data shows that many Midland residents have benefited from budget coaching and debt management plans, which provide structured guidance for repaying loans while maintaining financial stability. Ultimately, breaking the cycle of loan repayment stress in Midland is achievable through proactive measures, informed decisions, and access to the right support systems.
Midland residents facing loan repayment struggles are not alone, as the article has illuminated various factors within the region’s economic landscape contributing to these challenges. Midland title loans, while appearing to offer quick solutions, can exacerbate financial strain due to their high-interest rates and short-term nature. However, the piece also offers hope through practical strategies for residents to overcome these difficulties. Key insights include understanding one’s financial situation, exploring alternative loan options with lower interest rates, building an emergency fund, and seeking support from community resources. By implementing these measures, Midland residents can regain control over their finances and build stability for a more secure future. This article serves as a comprehensive guide, empowering readers to make informed decisions regarding their loan repayments and financial well-being in the context of Midland’s unique economic dynamics.